Our latest quarterly survey finds SME business confidence improved in the first quarter of 2023 but ‘cash crisis’ continues to impact business through reduced cash balances and ongoing cash flow worries
Need to know:
- SME business performance has stabilised
- Increased optimism for future trading outlook
- ‘Cash crisis’ continues with depleted bank balances and ongoing cash flow problems
- Spending and investment reduced to keep on budget
Having reached a record low in the last quarter of 2022, the outlook of the UK’s SME community has rebounded in the first of this year. According to Capify’s latest, SME confidence has improved in the first quarter of 2023 amid stabilising business performance and increased optimism for future outlook.
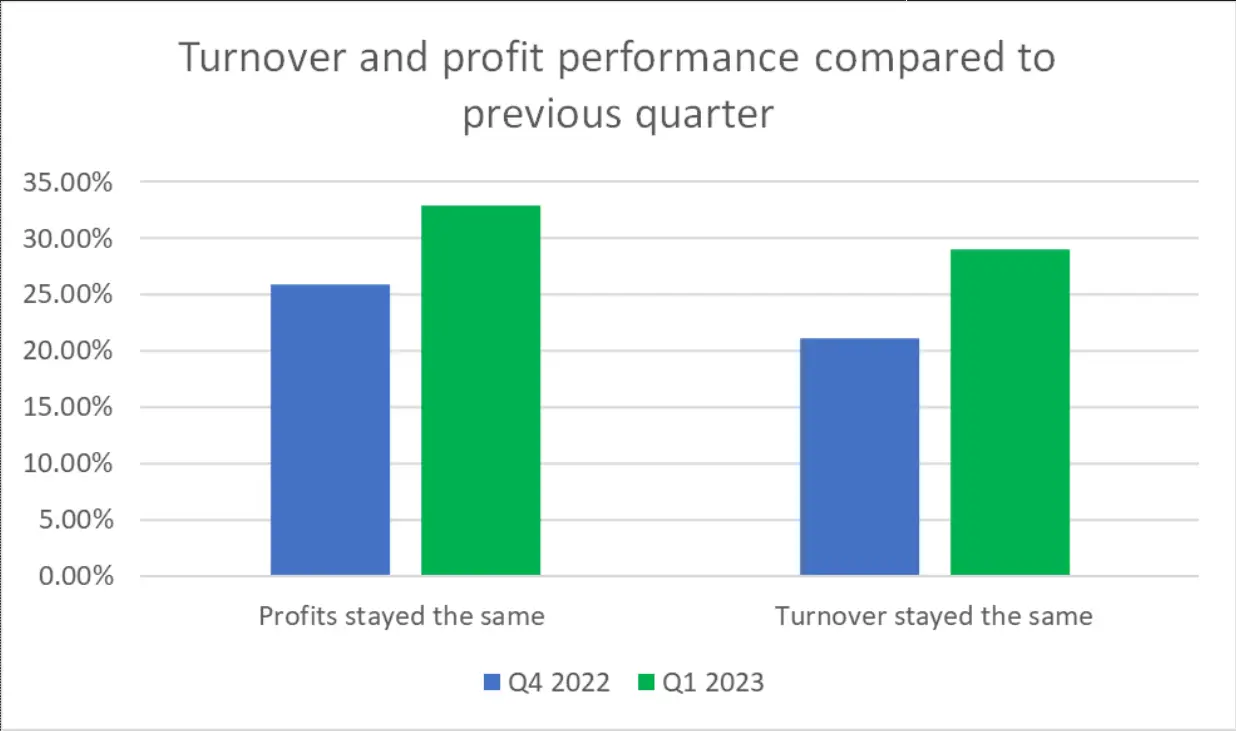
Released in March 2023, Capify’s SME Business Confidence Survey reveals a picture of increased stability in trading performance. One in three respondents saw turnover remain consistent with the last quarter of 2022, an increase of 8% on the period between Q3 and Q4 2022. The same number reported Q1 profit levels being consistent with the prior period, a 7% increase on the previous quarter-on-quarter level. These metrics combined to ensure 36% of respondents’ trading performance was currently in-line with targets for the year – an increase of 12% on the previous quarter.
Optimism ahead
Just under 60% of SME owners expect turnover to grow over the coming year, with 52% expecting profits to grow over the same period. This optimism about forthcoming business performance translates to an expected increase in hiring – 42% of firms expect to increase their headcounts over 2023, an increase of 5% on the previous quarter. Furthermore, this improved confidence in operating conditions, means that 51% of firms are planning business expansion over the next 12 months (compared to 46% in Q4 2022).
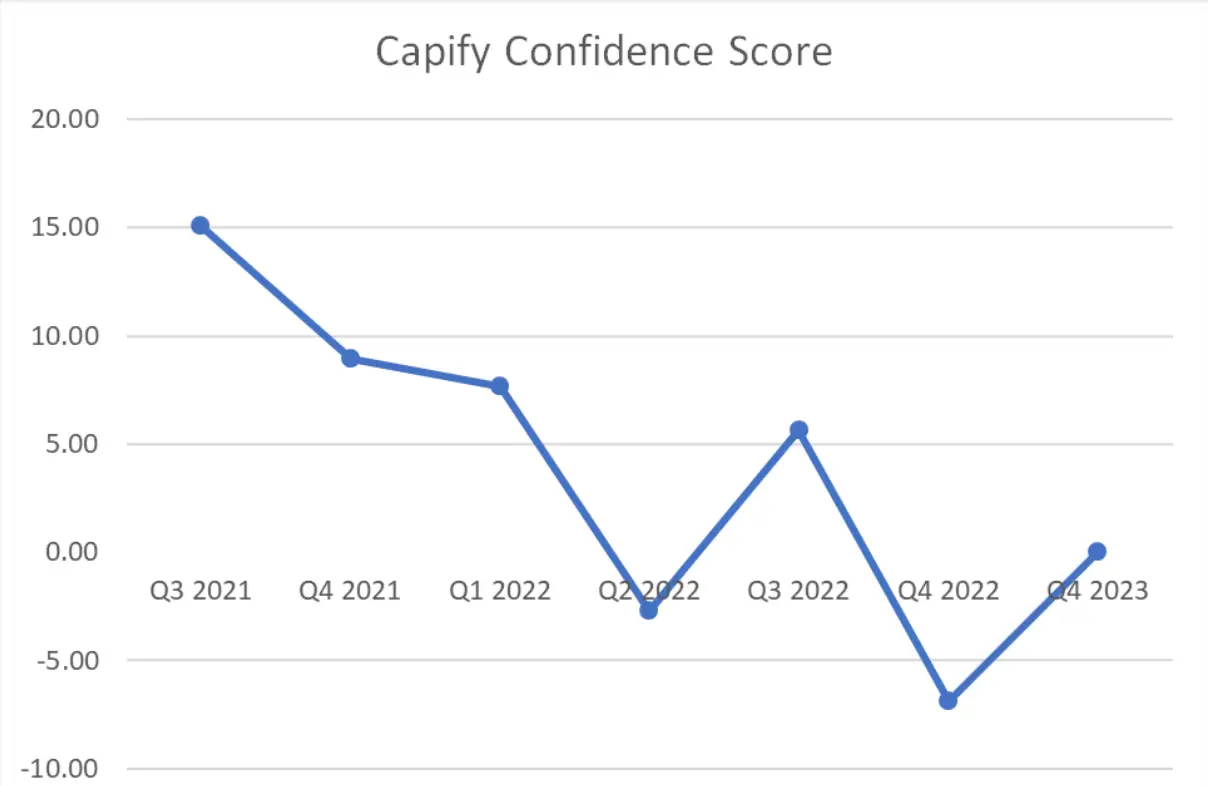
The survey, which canvasses the insights of hundreds of SME business owners from across the UK on areas of current business performance, trading forecast, and investment intentions, uses the data to produce an overall confidence score between -10 (very unconfident) and +20 (highly confident). The confidence score now sits at 0.12, a 7pp improvement on the Q4 2022 score of -6.89.
Turning a corner?
John Rozenbroek, CFO/COO at Capify, said: “Although still some way below the historic average confidence score, these latest results give some cause for optimism. UK SMEs have faced a raft of challenges and deteriorating trading performances over the past three years, but it seems that, for many, some of the key business metrics are stabilising.”
“We know that there are still significant challenges ahead, but steadier levels of turnover and profitability gives smaller businesses more confidence and that translates into the optimism we’re seeing in their future outlook.”
“Cash is the great enabler for SMEs but, cash flow issues and depleting working capital can put the brakes on even the most optimistic of businesses.”
Challenges prevail
Consistent with previous survey findings, cash flow challenges and cash reserves continue to be an issue for respondents. One in five SME owners cite cash flow as the reason preventing them from expanding their business, whilst just over a third of respondents cite cash flow as an ongoing worry.
Cash flow issues are an evergreen problem for businesses of all sizes, but they have been accentuated by the period of inflationary pressure in the economy. In response, the majority of firms (53%) have reduced spend on travel and entertainment whilst 39% have reduced spend on advertising and marketing.
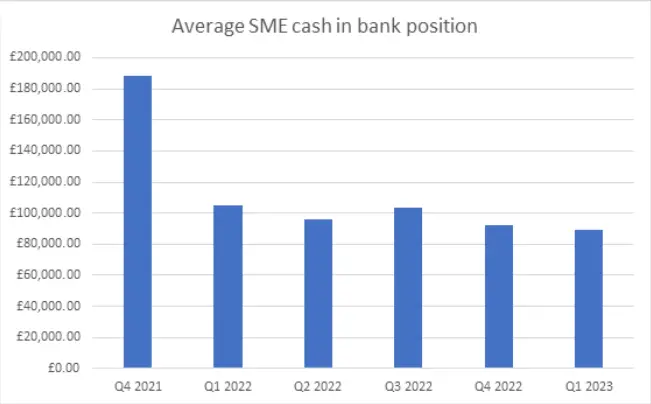
At the same time, the average level of cash in the bank for UK SMEs has fallen to its lowest amount since the survey began. Respondents reported an average bank balance of £89,534 – compared to an average of £99,212 across 2022.
Even with cost-cutting measures, one third of respondents have required external funding to support their operations, with 36% of respondents citing cash flow issues and depleted working capital reserves as the reason.
“We have witnessed a growing ‘cash crisis’ amongst UK SMEs for the past year”, says Rozenbroek. “We can see the impact that the economic conditions have placed on cash flow and cash balances and helping UK SMEs weather the storm is imperative.” “At Capify, we are passionate about serving the UK SME community. Our survey gives us the insights we need to address the uniquely challenging climate that SMEs are operating in. It is encouraging to see that confidence appears to be returning, but we need to ensure that optimism is matched by growing working capital, healthy cash flows, and access to finance, when required”
Capify offers a range of business loans to help support small businesses throughout their growth journey. Check to see if you’re eligible for one of our loans with our online eligibility checker. Or, if you’d prefer to talk to a member of our team, we’d be happy to guide you through the process. Give us a call today on 0800 151 0980.